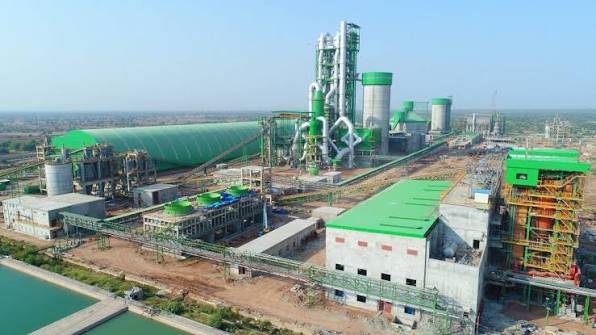
Pioneer Cement Ltd. (PIOC) recently held an analyst briefing to discuss its FY26 financial results and future outlook. In FY26, PIOC reported profit after tax (PAT) of PKR 6.6 billion, up 35.2% year-on-year. Earnings per share (EPS) rose to PKR 29.03, up from PKR 21.47 in FY25. Net turnover rose 15.8% year-on-year to PKR 38.6 billion, while gross profit grew 10.9% year-on-year to PKR 11.6 billion. However, EBITDA (Earnings Before Interest, Taxes, Depreciation, and Amortization) grew 8.6% year-on-year to PKR 13.7 billion, but the EBITDA margin fell to 35.6% from 38.0% in FY25. AL Habib Capital Markets attributed this decline to higher input costs.
Profitability improved on lower finance costs and higher other income. Finance costs declined 55.1% YoY to PKR633mn, while other income rose 93.0% YoY to PKR487mn. Consequently, profit before tax increased 25.8% YoY to PKR10.2bn, supporting 35.2% growth in net earnings. PIOC strengthened its balance sheet by eliminating outstanding debt, with total banking debt declining from PKR8.89bn in FY25 to nil in FY26. The debt-free position as of June 30, 2026, further reduced finance costs and enhanced financial flexibility.
Cement dispatches recovered in FY26, with domestic sales rising 18.0% YoY to 2.45mn tons from 2.07mn tons in FY25. Production increased to 2.45mn tons from 2.09mn tons, reflecting improved capacity utilization and demand. Management expects cement demand to grow by 7–9%, supported by PSDP spending, subsidized housing finance schemes, and private residential and commercial construction.
PIOC’s existing captive power capacity stands at 48MW, comprising an 18MW waste heat recovery plant (WHRP) and a 30MW coal-fired power plant.
The company is expanding its renewable energy capacity with a 28.265MW solar power project, expected to become operational this quarter. The project aims to diversify the energy mix, reduce reliance on conventional power sources, and improve long-term cost efficiency.
Grid electricity costs approximately PKR 26/unit, offering potential savings where it is cheaper than captive generation. Grid power currently accounts for around 67% of PIOC’s electricity mix, with the remainder supplied by waste heat recovery (WHR).
The average retention price stood at PKR 15,781/ton.
